The FinNLP Group, led by Prof. Yi Yang at HKUST, develops NLP and AI methods for finance. Our research spans Financial LLM/Embedding, Textual Factors & Return Predictability, and Risk Forecasting & RL for Asset Allocation—from building financial language models to extracting signals from corporate disclosures 10-K filings, earnings calls, and macroeconomic narratives. We are excited to apply and scale our research with industry partners.
Financial LLM/Embedding
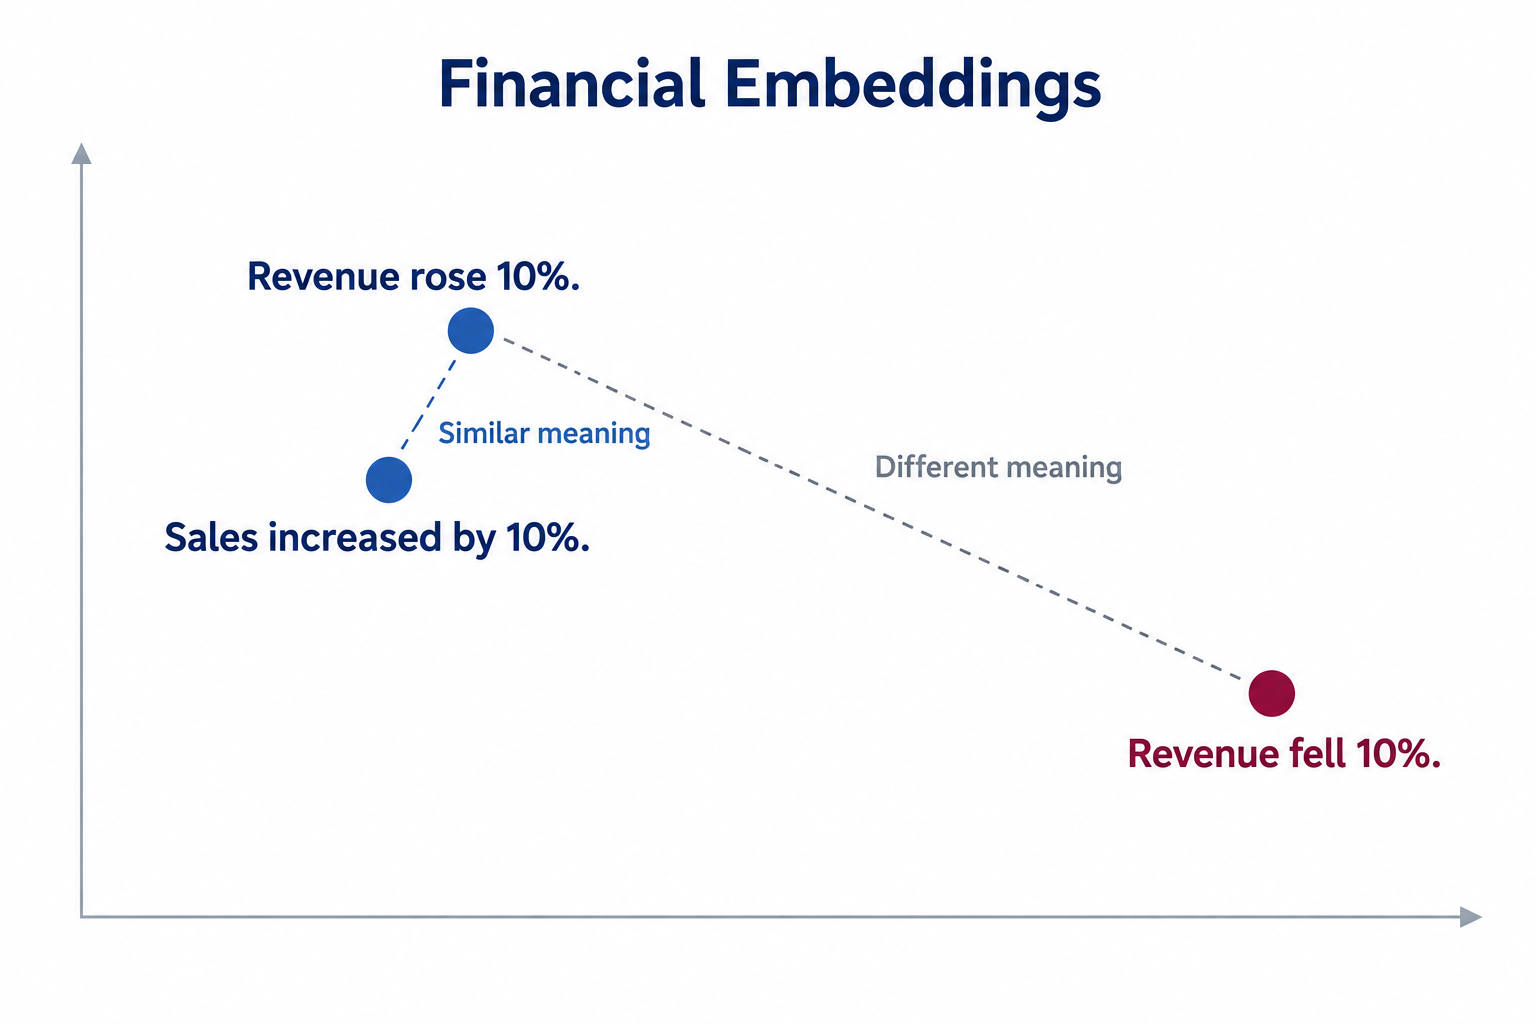
We develop foundation models for understanding financial language. FinBERT extracts information and sentiment from financial text. InvestLM adapts large language models to investment tasks through financial instruction tuning. FinMTEB / FinE5 provides a benchmark and an embedding model for financial text representation and retrieval. View more.
Textual Factors & Return Predictability
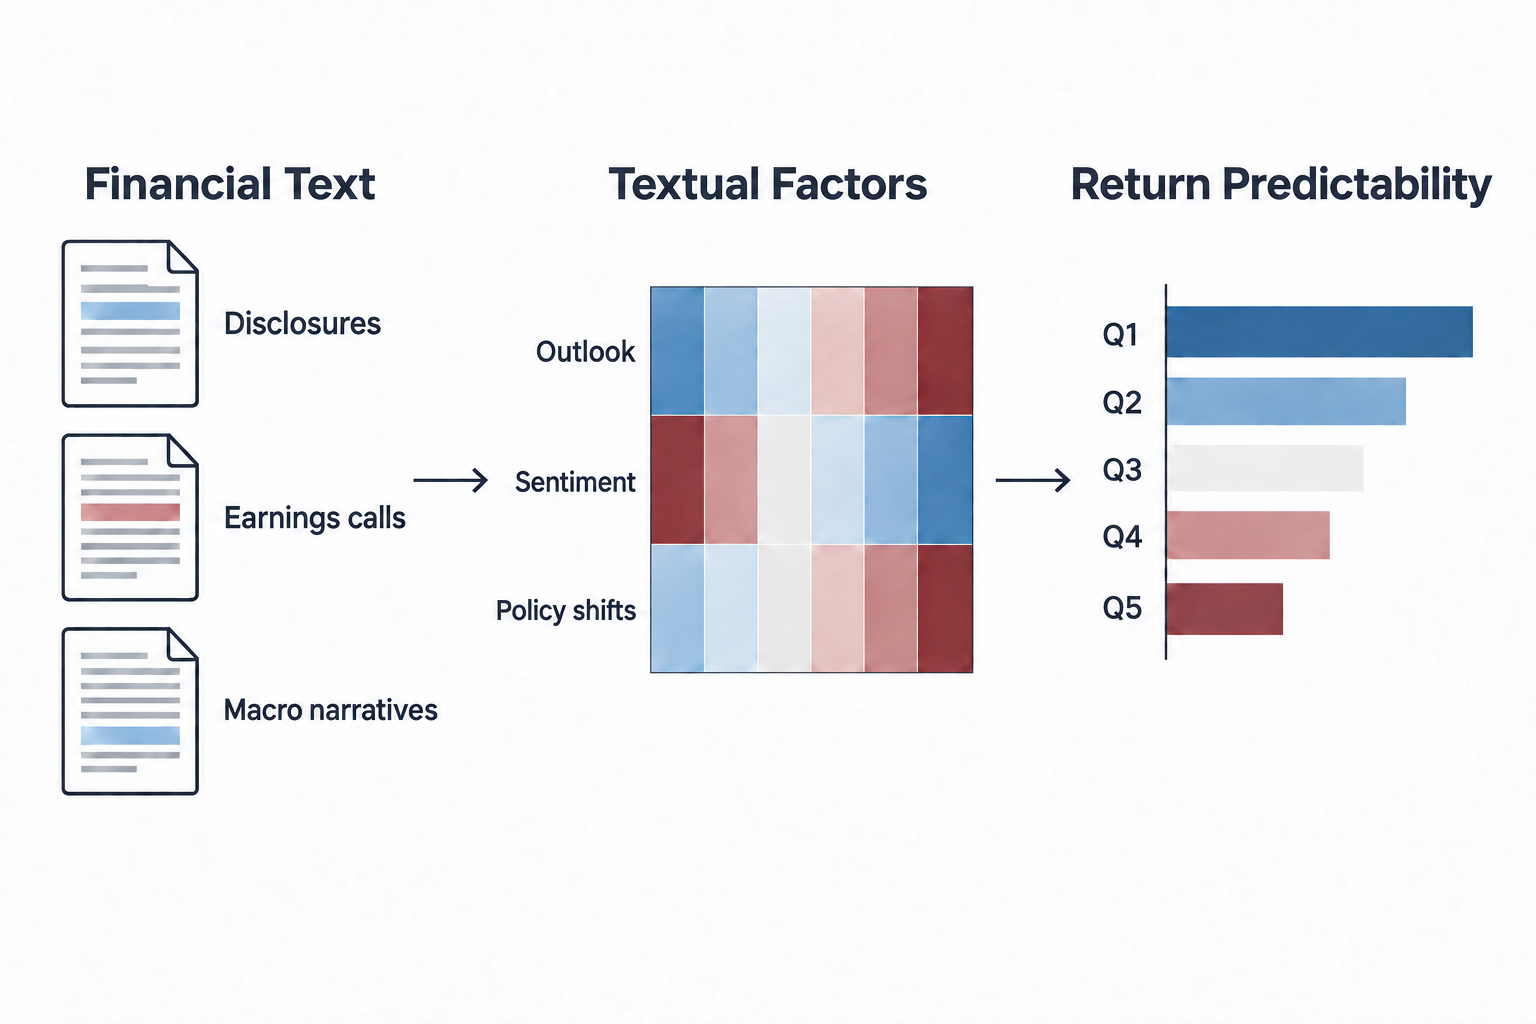
We extract factors from financial text and study their value for return prediction and asset ranking. Mind the Shift measures changes in monetary policy stance, while Departures from Routine Disclosure measures changes in management outlook. Our ranking methods include LambdaRankIC, which directly optimizes Rank IC, and FinRankGRPO, which trains LLMs for listwise financial asset ranking. View more.
Risk Forecasting & RL for Asset Allocation
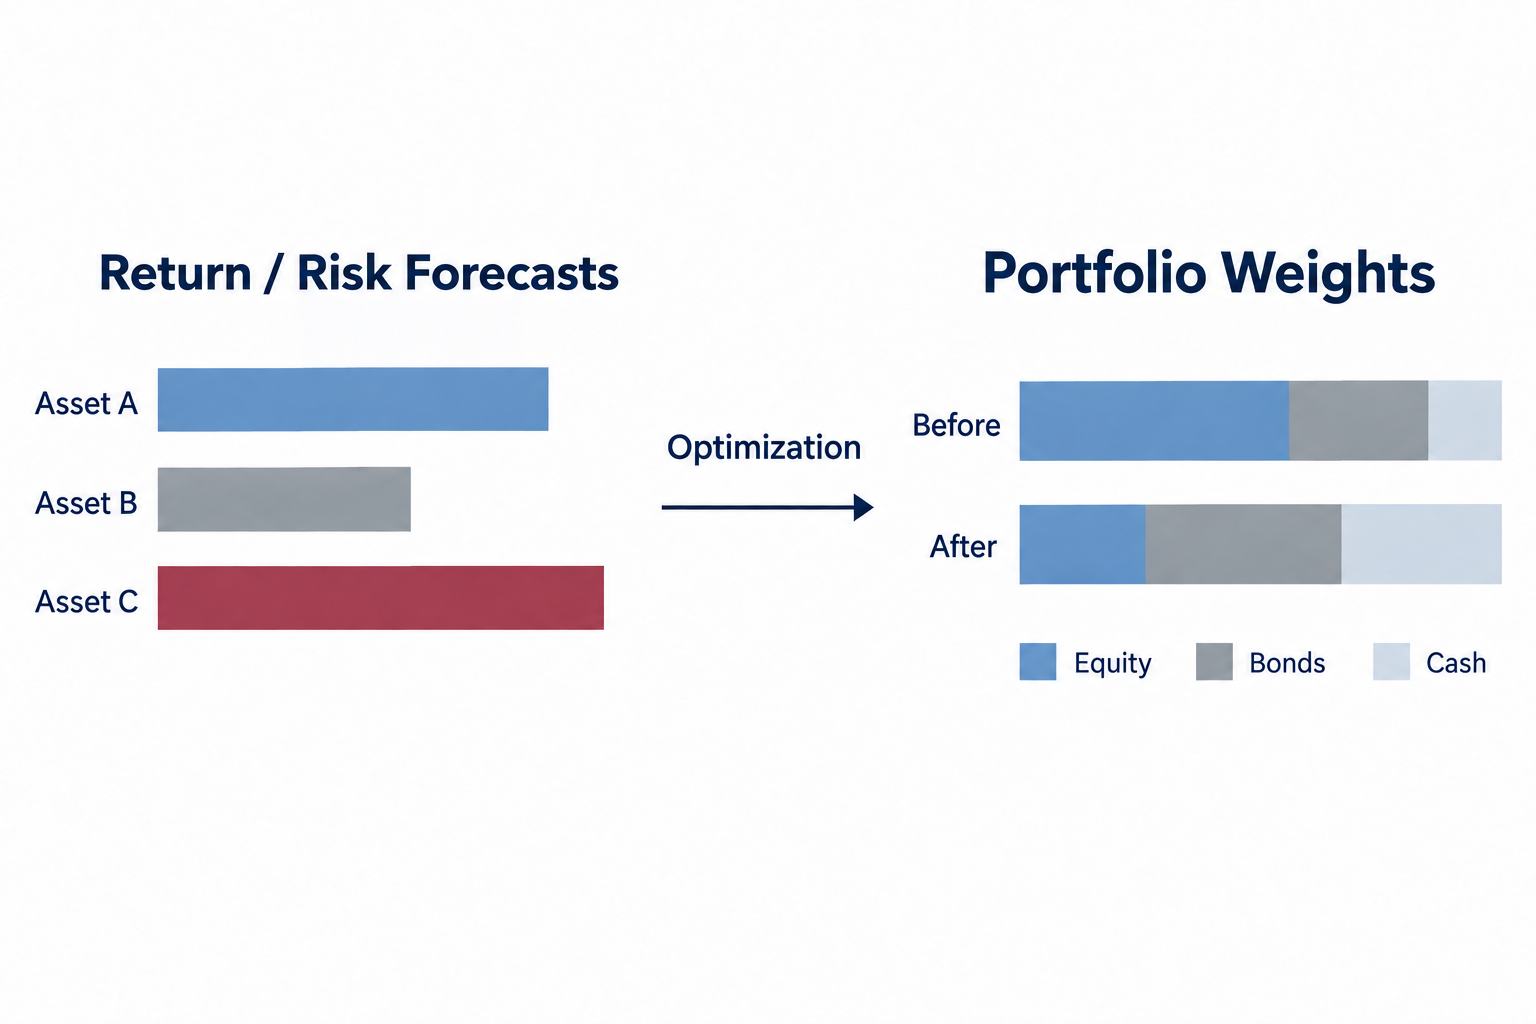
We use financial disclosures, earnings calls, and macroeconomic narratives to support risk management and assect allocation. Divide-and-Contrast predicts firm market risk from text, and Learning from Earnings Calls models earnings conference call structure. MacroAllocAgent translates macroeconomic narratives into strategic asset allocations. View more.